
Curling betting tips 2026 — how to read the market before staking
 Available in US
Curling is a niche in British sportsbooks — small margins on the screen, fat margins in the price — and the work behind any “tip” is the same work that sits behind a tip in any other sport: form, fixtures, line-ups, the bookmaker’s own margin, and the discipline to stop when none of those line up. This guide is built around that. It explains how a curling market is set, how a price is built around a margin, how a punter reads value without being sold a winner, and what each of the featured British bookmakers actually does on its own licence and its own terms. It does not name a winner of any match and never will: no published set of tips can know an outcome, and the page that pretends to is the page that costs its reader money.
Data current as of 27 October 2026. Licensing claims verified against the Gambling Commission’s public register.
Legality and what a Gambling Commission licence covers in Great Britain
A bookmaker taking bets from customers in Great Britain needs a Gambling Commission licence, whatever its corporate address says. That is the rule the Gambling (Licensing and Advertising) Act 2014 added to the Gambling Act 2005: the test is where the bet is placed, not where the company sits. A Gibraltar or Malta licence is not a substitute for a Commission licence. Operators based outside the UK have held British licences since the rule changed, and operators based inside the UK still need one. There is no state monopoly and no cap on the number of licences — the register lists hundreds of remote holders — so a brand calling itself “the only licensed one” is making a claim the register does not support.
The Commission issues licences by category. The relevant one for an online bookmaker is the *remote general betting standard* licence for real events, which covers pre-match and in-play markets on actual sporting contests. Betting exchanges — places where customers bet against each other rather than against the house — hold a separate *remote betting intermediary* licence. Pool betting on horse and dog racing sits in its own licence class. Financial spread betting is regulated by the Financial Conduct Authority, not the Commission. Each operator card in this guide states the licence category it actually holds.
Age and identity: the minimum age for gambling in Great Britain is 18. Since 7 May 2019 every licensed operator has to verify a customer’s name, address and date of birth before the first deposit, and before the first bet including a free bet or bonus bet. No anonymous play exists at a licensed site. A credit card cannot be used for gambling in Great Britain — the ban took effect on 14 April 2020 and covers credit-card-funded e-wallet top-ups as well. Debit cards and bank transfers are not caught by the ban. The check is one of the costs of using a licensed brand; it is also the reason a licensed brand can offer the player protections the law attaches to a licence.
The public register is the test of who holds a licence. It is searchable by business name, trading name, domain or account number, and a brand holding a valid entry on the day a bet is placed is a brand holding a valid licence. Licensed operators use .com and .co.uk interchangeably, so the domain by itself proves nothing. A punter checking a brand for the first time should look the licence number up on the register rather than trust a banner on the brand’s own site.
What the licence does not do: there is no statutory list of permitted bets or markets in Great Britain. An operator decides what to offer inside its licence category and inside the Licence Conditions and Codes of Practice. There is no statutory cap on stakes — bookmakers set their own maximum bets, and they restrict customers they choose to restrict. In-play betting is offered under the operator’s licence conditions, and writing that in-play is “unrestricted” in law is not a fair summary: the controls are licence conditions and operator practice, not a statute that says “in-play is open”.
The frame, in one line: licensed brands are subject to identity checks, stake and bonus rules, GAMSTOP, and the Commission’s enforcement; unlicensed brands offer none of those protections and have no British route for complaints if funds are withheld. Neither is “the safe choice” by default — the trade-off is real, and it runs in both directions.
Responsible gambling, safer play and where help comes from
The safer-gambling side of a British licence is a stack of rules, each with a date attached, and the stack has thickened over the last few years. The headline items the punter meets first are GAMSTOP, the financial vulnerability check and the deposit-limit rules.
GAMSTOP is the national multi-operator online self-exclusion scheme. Every online operator licensed by the Commission has been required to take part in it since 31 March 2020. A customer registering with GAMSTOP chooses a period of six months, one year, five years, or five years with auto-renewal; the exclusion applies across every participating site and app, and after the minimum period it stays in place for a further seven years unless the customer asks GAMSTOP to remove it. Betting shops run a separate in-shop self-exclusion scheme, so GAMSTOP is the online route, not the shop one.
The financial vulnerability check is a Commission licence condition that took effect on 30 August 2024 and is being applied in stages. For remote betting, it triggers once a customer’s deposits minus withdrawals cross £150 in a rolling 30-day window (in force since 28 February 2025). It is a public-record check — bankruptcies, county court judgments and the like — not an income check and not a credit reference check. The financial risk assessments that the press calls “affordability checks” sit behind the vulnerability check in a staged plan the Commission set out on 7 July 2026: announced, staged, no start date. A punter should not be told by this page that affordability checks are in force — they are not, yet.
Deposit limits are a separate Commission requirement (Remote Technical Standards 12). Operators must offer a gross deposit limit on a fixed time frame, and the first changes have applied since 31 October 2025. A second phase was postponed to 30 September 2026 and whether it has gone live on that date is not established. There is no state-set deposit or loss ceiling for betting in Great Britain: the limits a punter sets are the punter’s own choice, and an operator offering a tool to set them is meeting a duty, not setting a state rule.
The bonus cap is the marketing-side rule. Wagering requirements on bonuses are capped at 10x since 19 January 2026, so a £10 bonus at 50x — £500 of qualifying bets — is no longer permitted; under the cap no more than £100 of qualifying bets per £10 bonus. Mixed-product promotions, the “bet on football to get free spins” shape that ties betting and casino together, are banned in the same package. The cap’s treatment of free bets with no wagering condition and any cap on the money value of a bonus are not established, and a punter should read the offer terms before claiming.
Where to get help: GamCare runs the National Gambling Helpline, GambleAware signposts treatment and advice, the NHS runs gambling clinics in parts of England, and Gamblers Anonymous runs peer-support meetings. Most licensed operators link to at least GamCare and GAMSTOP from their safer-gambling pages, and several feature those links prominently on the home page itself.
Spread betting, separately. One of the featured brands in this guide — Spreadex — runs financial spread betting alongside fixed-odds sports betting. The two activities are regulated by different bodies: fixed-odds by the Gambling Commission, financial spread betting by the Financial Conduct Authority. Spread betting is leveraged, and losses on a spread position can exceed the original deposit, which is not the case for fixed-odds betting. The shape of the risk is different, the regulator is different, and the two products are not interchangeable.
Curling as a sport and what a market actually prices
The sport, in the betting-relevant pieces
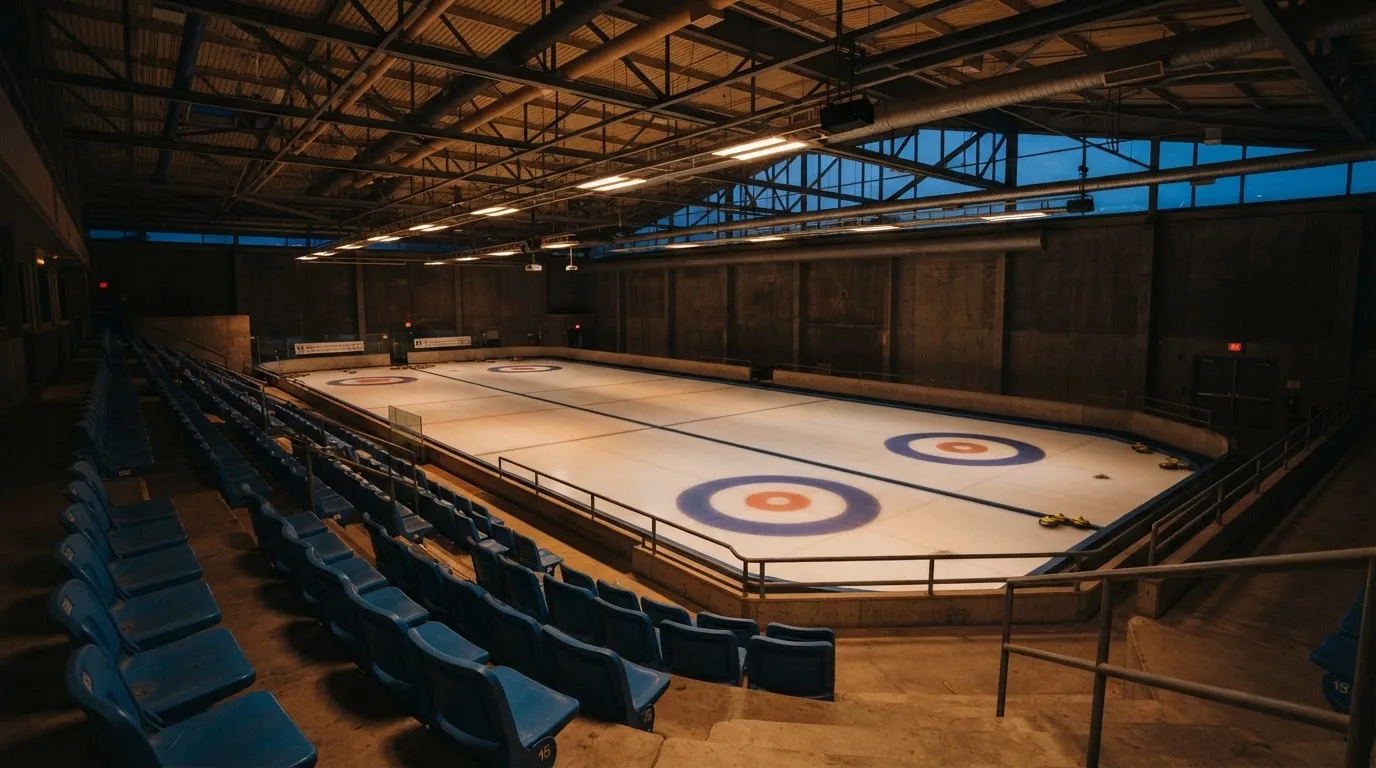
Curling is a four-player team game — two in mixed doubles — played on a sheet of ice roughly 45 metres long with a circular target at each end called the house. Each team has eight stones, two per player, and the sides take turns sliding stones down the sheet towards the button at the centre of the house. An end is complete when all sixteen stones have been thrown. The team with the stone closest to the button scores one point for each of its stones sitting closer than the opponent’s nearest stone; only stones inside the house count. A standard game runs eight or ten ends — competitive international play usually goes to ten — and tied games go to extra ends until one side leads after a complete end.
The hammer is the last stone of an end, and possession of it swings end to end: the hammer goes to the team that did not score in the previous end. If an end is blanked — every stone knocked out of the house, or no stone left inside it — the hammer stays where it was. Hammer advantage matters at the betting level because the team with last stone controls the geometry of the final end, and most competitive games are decided in the last two ends when the hammer team either scores one or steals nothing. A market that prices only the match winner is throwing away the most common lever a tipster can name.
Curling stones weigh between 17.24 and 19.96 kg under World Curling Federation rules — the figure runs 38 to 44 lb in imperial — and the ice is “pebbled” with water droplets before each game to control the curl of the stone. The details do not change the price, but they explain why a curling match looks slow on screen and is structurally faster to read than a viewer expects: most ends take four to five minutes of throw time and the thinking in between is where most games are won.
Curling has been an official Olympic medal sport since the 1998 Winter Olympics and mixed doubles has been held at the Olympics since 2018. The international calendar runs year-round through the World Curling Tour and the Continental Championships, with the World Men’s, World Women’s, World Mixed Doubles and World Senior Championships as the headline events. The European Curling Championships sit alongside as a second tier of competition. None of this happens every week, which is one of the reasons curling markets are thinner than football markets: the fixture list is short, the line-up news is local, and most bookmakers price only the headline events.
Understanding market volatility and match outcomes
For a match outcome bookmaker offers three lines, sometimes two. Match winner (outright) is a two-way market for most events: one side to win, the other to win, draw no bet for a tied game that does go to extra ends — and the operator’s settlement decides whether the draw-no-bet stake is returned or the match is settled as a winner after extras. Outright tournament winner is the futures market for the side to win the whole championship, and prices run from a few percent for the favourite to a hundred-to-one or more for a qualifier making a deep run. Handicap / spread prices a side with a stones-and-ends head start in a single match, useful when one team is significantly stronger and the outright price has run short. Total ends markets price over/under on the number of ends played, with extra ends priced separately or rolled into the total.
The thinner the market, the wider the bookmaker’s margin. This is the single most important fact about curling betting, and it follows from how markets are made: a bookmaker takes a position and prices it from its own model, not from a balanced book of punters on both sides. A Premier League football match has hundreds of prices from dozens of operators, and the margin is thin — 2–5% on the outright 1X2 — because the bookmaker is competing to take the other side of a position the public is already taking. A curling match at the European Championships might have one price from one operator, and the margin on that price is wider because the operator has not had to compete the margin down. A punter betting curling should assume the overround is heavier than a Premier League price at first glance and read the margin before reading the price.
A bookmaker’s margin is the operator’s take on a market. It is built into every price: a 5% margin means a 95% payout on a perfectly balanced book, and a 10% margin means a 90% payout. The margin is invisible in any single price — a 1.90 looks like a 1.90 — but it shows up as soon as you turn the prices into probabilities and add them together. A two-way market at 1.90 / 1.90 implies a probability of about 52.6% on each side; add them and the total is 105.3%, and the 5.3% overround above 100% is the premium the house takes. That is the shape of any price a punter reads.
The page’s own illustrative calculation: an example two-way market at decimal odds 1.90 on each side. The implied probability on each side is 1 ÷ 1.90, which is 52.63%; adding both sides gives 105.26%. The bookmaker’s margin on this market, taken across the book, is between roughly 5% and 5.3% — a band, not a point, because in practice the book is not perfectly balanced and the realised margin drifts. The point is the geometry: any market priced shorter than 1.90 / 1.90 carries a wider margin, and any market priced longer than 1.90 / 1.90 carries a tighter one. A 2.00 / 2.00 book is closer to 100%, which is closer to break-even; a 1.50 / 3.00 book is much further from it, and the favourite’s price is doing most of the margin work.
What “value” means when no tip is certain
A value bet is a price that is higher than the true probability of the outcome, once the bookmaker’s margin has been taken out. The arithmetic is plain: turn the price into a probability (1 ÷ decimal odds), subtract the share of the margin that sits on that side, and compare what is left with your own estimate of the chance. If your estimate is 60% and the price implies 50%, the bet has value. If your estimate is 45% and the price implies 50%, the bet is negative value and the right answer is to skip it.
Three honest points follow from that. First, no published estimate of true probability is anything more than an estimate — a model, a form line, a line-up read, a feeling sharpened by years of watching the sport. Second, the bookmaker’s margin is on average the punter’s tax: over thousands of bets, a punter backing only prices that are positive value is the punter who pays margin only on the bets he takes and skips the bets that carry only margin. Third, no value bet wins for certain. A 60%-chance bet loses four times in ten, and a tipping record that names losers as winners to keep the strike rate looking high is not a record, it is a marketing claim. A punter who treats every tip as one in a series, not as a single must-win, is the punter whose bankroll survives the variance.
In a sport as thinly priced as curling, the margin on a match market is wider than the margin on a Premier League match, and the edge a punter can find is wider to match. The arithmetic of value still holds: a price of 3.00 implies a 33.3% chance, and a punter who thinks the chance is 40% has found 6.7 points of value after margin. The catch is that the punter’s own estimate is built from thinner information — a curling team’s form might be two sheets of headline matches over the last six months, not the hundreds of fixtures a football model has — and the variance around the estimate is wider. Value is a probabilistic edge, not a guarantee.
The shortlist of British bookmakers for curling in 2026
The ten brands in this comparison are all listed on the Gambling Commission’s public register against a licensee holding a remote general betting standard licence (real events) for Great Britain. Several also hold the betting-intermediary category where they run an exchange. A place in this comparison is not a licence, and an operator’s own terms — not the comparison’s column headings — are the source of truth on each offer.
The table is laid out so a punter can scan licence status and the operator’s own terms on the book’s curling coverage side by side. The licence number is the register entry; the licence holder is the company named on the register; the third column carries what the operator’s own site or app store listing states about its curling offer, where it states one. Where a brand does not state a curling position in its own terms, the cell carries a marker rather than a guess.
| Bookmaker | Gambling Commission remote licence and holder | What the operator’s own terms state about curling |
|---|---|---|
| Kalooki Sportsbook | 057730-R-333396-005 (account 57730) — Kalooki Sportsbook Limited | No curling position stated in current terms |
| Octobet | 062545-R-337248-006 (account 62545) — Octopus Game Limited | No curling position stated in current terms |
| William Hill | 039225-R-319373-015 (account 39225) — WHG (International) Limited | No curling position stated in current terms |
| Bet Ahoy | 100094-R-341742-003 (account 100094) — Bet Ahoy Ltd | Curling listed among sports covered, per the brand’s app listing |
| Betfred | 039544-R-319290-010 (account 39544) — Petfre (Gibraltar) Limited | No curling position stated in current terms |
| Matchbook | 039504-R-319407-024 (account 39504) — Triplebet Limited | No curling position stated in current terms |
| Star Sports | 009177-R-104555-019 (account 9177) — Star Racing Limited | No curling position stated in current terms |
| BetUK | 039198-R-319450-029 (account 39198) — LeoVegas Gaming PLC | No curling position stated in current terms |
| Tote | 054779-R-331321-008 (account 54779) — TDCO Limited | No curling position stated in current terms |
| Midnite | 101839-R-342850-001 (account 101839) — Midnite Limited | No curling position stated in current terms |
The table is built from the register and from each operator’s own terms. The register entry is the test of licence; the operator’s own terms are the test of what it prices. A punter choosing a brand for curling betting should treat the absence of a stated curling position as a reason to check the operator’s Wettprogramm — the operator’s own sports menu, in-app or on the web — before staking, not as a reason to assume curling is absent.
Two structural notes on the comparison itself. First, several of these brands share a parent licensee — BetUK sits under LeoVegas Gaming PLC, William Hill sits under WHG (International) Limited — and the comparison treats them as the independent brands their trading names describe, because that is how a punter meets them at the betting slip. Second, Matchbook is the only brand in the table holding the betting-intermediary category alongside the general betting standard licence, because Matchbook runs a betting exchange; the other nine are fixed-odds bookmakers on their own general betting licence. The price shape on an exchange is set by punters backing and laying, not by an operator’s trading desk, and the comparison’s third column carries that distinction where it affects what a punter reads.
What each featured bookmaker actually does
The reviews below stick to what each operator’s own site, app store listing or register entry states, and they close on a judgement of what the brand is for in this comparison. Each block is built around the operator’s licence, its stated sports menu, the part of its offer that a curling punter is most likely to meet, and the trade-off that comes with choosing it. The same facts do not appear on every block: the licence line is given in full on the first appearance and shortened on later appearances, and the offer terms are described, not printed.
Kalooki Sportsbook
Kalooki Sportsbook is operated by Kalooki Sports Book Ltd (company number 12938274) under Gambling Commission account 57730, the licence sitting under Kalooki Sportsbook Limited on the public register. The brand is a GAMSTOP participant, which puts it inside the Commission’s online self-exclusion regime alongside every other licensed remote operator. Identity is verified before a first deposit, in line with the Commission’s identity-check rule; that is a condition of the licence rather than a feature of the brand.
A curling punter looking at Kalooki is buying into a smaller brand with a UK-registered operating company and a clean licence position. The trade-off is reach: a smaller sportsbook tends to carry a tighter menu than a William Hill or a Betfred, and a curling fixture list on a brand of this size is most likely to show only the headline events — the World Championships and the Olympic tournament. For a punter who bets curling once a year at the Olympics, that menu is enough; for a punter who follows the Continental Tour, the menu is thin. The brand suits the casual curling punter who values a UK operator with a plain corporate structure over the depth of the majors’ sportsbooks.
Octobet
Octobet’s sportsbook welcome offer is structured as 50% back as a free bet up to £50, plus a £10 casino bonus for new customers, according to the brand’s GB app store listing. The licence sits under Octopus Game Limited against Gambling Commission account 62545. As with every licensed remote operator, the brand is part of the GAMSTOP scheme and verifies identity before a first deposit.
The casino bonus attached to the sportsbook welcome offer is a mixed-product promotion under the Commission’s January 2026 marketing rules, and a punter looking at this offer should read the small print: a mixed-product promotion that requires gambling on two or more product types — for example, betting on football to claim free spins on a slot — is banned in Great Britain, and a betting offer that bundles a sportsbook free bet with a casino bonus is the shape the ban targets. The same offer may still be structured around an opt-in where the casino element is optional; the small print is what settles it. The brand suits a punter who wants the sportsbook side of the welcome and is happy to treat the casino bonus as a separate, optional add-on.
William Hill
William Hill is one of the longest-standing British bookmakers and sits under WHG (International) Limited on the Commission’s register against account 39225. The brand’s Best Odds Guaranteed applies to UK and Irish horse racing from 8 AM on the day of the race, on both single and multiple bets, and not to ante-post, tote or pari-mutuel bets. That rule is specifically a horse-racing feature and does not carry over to curling — a curling fixture is settled at the price taken at bet placement, with no BOG uplift — but the brand’s general market depth carries over.
William Hill’s sportsbook is the broadest in this comparison by a margin, and a curling punter looking for outright tournament winner markets and match markets on the headline championships is most likely to find them here. The trade-off is scale: a larger operator prices more markets but offers less personal service than a phone-led brand like Star Sports, and the welcome offer terms are heavier in turnover conditions than smaller brands’ offers typically are. For a punter who bets several sports and wants a single account to cover all of them, William Hill is the safe generalist pick; for a punter whose betting is curling-only, the brand’s scale is wasted on the sport.
Bet Ahoy
Bet Ahoy’s welcome offer is structured as “Bet £10 & Get £10 in Free Bets”, made up of a £5 sports bet and a £5 acca. The licence sits under Bet Ahoy Ltd against Gambling Commission account 100094. Curling is listed among the sports covered by the brand — the only brand in this comparison whose listing states a curling position positively.
A punter looking at Bet Ahoy is buying into a smaller brand with a stated curling position and a simple welcome offer. The £10 free bet bundle is split between a sports single and an acca, which suits a punter who bets accumulators rather than singles; a punter betting curling at match level — a single on the outright or on the spread — gets the sports-bet leg of the bundle, not the acca. The brand suits a curling punter who wants a small bookmaker with curling on its menu and is happy to take the welcome offer as it is split.
Betfred
The Betfred Sports, Casino & Games app is published by Done Brothers (Cash Betting) Ltd, with the remote betting licence held by Petfre (Gibraltar) Limited against Gambling Commission account 39544. The app covers 21 sports plus over 2,000 casino-style games. Betfred is one of the larger British high-street bookmakers turned remote operator, and the brand’s sportsbook carries the depth that comes with that history.
A curling punter at Betfred is betting through a sportsbook built around British racing, and the curling menu is most likely to follow the headline events — the World Championships, the Olympics, the European Championships. The trade-off is that Betfred’s mobile product is broader than curling-only and the in-app navigation is built around horse racing first; finding curling on the app is a matter of searching the sport menu rather than finding it on the home page. The brand suits a punter who spends most of their time on horse racing and treats curling as a secondary, occasional interest.
Matchbook
Matchbook is a betting exchange where customers bet against other users, with Bet Builder, multiples, in-play betting and live streaming of horse racing and greyhounds. The licence sits under Triplebet Limited against Gambling Commission account 39504, and the register lists the betting-intermediary category alongside the general betting standard licence — the latter for the fixed-odds and multiples product, the former for the exchange.
A punter looking at Matchbook is meeting a different kind of price: on an exchange, prices are set by other punters backing and laying, not by an operator’s trading desk. The bookmaker’s margin on an exchange comes from commission on net winnings rather than from an overround on the price, and the effective margin is typically thinner than a fixed-odds bookmaker’s margin on the same event. The trade-off is liquidity: a curling market on an exchange is thinner than a Premier League football market on the same exchange, and a punter who wants a £500 stake at the displayed price may find only £80 moves at that price and have to walk away. Matchbook suits the experienced punter who wants thin margins and is comfortable sizing bets to the liquidity of the market; it is not the place for a curling punter who wants to stake a large single on a low-liquidity match.
Star Sports
Star Sports runs a phone-led service alongside its app and site: customers can speak to a trader directly on 08000 521 321 to open an account, place bets or ask customer queries, and the brand also offers support at [email protected]. The licence sits under Star Racing Limited against Gambling Commission account 9177. The phone-trading model is the brand’s defining feature and the one that does not exist at any of the other nine brands in this comparison.
A curling punter who wants to place a bet with a human trader rather than through an app is buying a service the other nine brands do not offer. The trade-off is reach: a smaller sportsbook with a phone-led model prices fewer markets than a William Hill or a Betfred, and curling is most likely to be available only on the headline championships and at the outright tournament level rather than on every Continental Tour event. The brand suits a curling punter who prioritises personal service over the convenience of a 24/7 app, provided they are happy to bet during business hours.
BetUK
BetUK’s sports welcome offer is structured around a £10 qualifying bet placed within 7 days of registering, with four £10 free bets returned — two football accumulators of 4+ selections and two multiples of 2+ — valid for 7 days and requiring an opt-in. The licence sits under LeoVegas Gaming PLC against Gambling Commission account 39198. The LeoVegas parent group is a Maltese-incorporated gaming operator with a British remote betting licence for the BetUK brand.
A curling punter looking at BetUK is buying into a brand whose welcome offer is built around football accumulators and football multiples. A curling-only bettor does not get the full value of the welcome, because the free bets are paid out as football-specific tokens rather than as sportsbook-wide credits; the qualifying £10 bet can be on curling, but the four £10 free bets are football-shaped.
Tote
Tote sits under TDCO Limited against Gambling Commission account 54779. The Tote brand is best known for pool betting on British horse racing, with a separate licence class for pool betting alongside the general betting standard licence for sports. Pool betting settles at a dividend declared after the race, not at a fixed price taken at bet placement, and the shape of a Tote bet is unlike a fixed-odds single: the punter is in the pool, not against the bookmaker.
A curling punter at Tote is betting into a brand whose strength is pool betting and whose sportsbook is the smaller part of the offer. The brand is most likely to price curling only at the outright tournament level rather than on individual matches. The trade-off is the dividend model: the return on a pool bet depends on the size of the pool and the stake taken on the winner, not on a fixed price, and a punter looking for the certainty of a quoted decimal price will not find it. Tote suits a punter who already bets into Tote’s horse-racing pools and is happy to add a curling outright to the slip; it does not suit a curling-only punter.
Midnite
Midnite’s site cites Gambling Commission licence 101839 and shows in-play events, an acca builder, popular accas and price boosts with maximum-stake limits, per the brand’s own home page. The licence sits under Midnite Limited on the register against the same account number. Midnite’s sports welcome offer is structured around a £5+ pre-match qualifying bet at EVS (2.0) or greater within 14 days of sign-up, returning £25 in free bets and 50 free spins valid for 7 days, per the brand’s GB app store listing. The free spins attached to the offer are casino-shaped rather than sports-shaped, and a curling punter should read the offer terms for the mixed-product treatment under the January 2026 marketing rules — the same point that applies to Octobet’s offer above.
A punter looking at Midnite is buying into a newer-generation sportsbook with acca-led market presentation: the home page leans on accumulators and price boosts rather than singles, and the in-play product is built around the same accumulator-first framing. The trade-off is breadth: a smaller, newer brand with a curated menu is most likely to price curling only at the headline events, and the acca-led framing does not fit a curling single. Midnite suits a punter who bets accumulators across several sports and is happy to take curling as one leg of a multi; it does not suit a curling-only punter betting singles.
How a price is built and what it costs
A price on a curling match is a decimal number — 2.50, 3.75, 1.85 — and it means a £10 stake returns £25 if it wins, £37.50 if it wins at the second, and £18.50 if it wins at the third. The return is stake times the decimal odds; the net profit is stake times the odds minus one. On a £100 stake at 3.50, the return is £350 and the profit is £250; on a £10 stake at 1.50, the return is £15 and the profit is £5. British bookmakers also publish fractional odds — 5/1, 11/4, evens — and the conversion is fraction plus one (5/1 is 6.00, 11/4 is 3.75, evens is 2.00). A price shorter than evens is “odds-on” and a price longer than evens is “odds-against”; the boundary is 2.00 in decimal form.
A combination bet multiplies the prices of its legs into one price. A double at 2.00 and 3.00 is a 6.00 combination; a treble at 2.00, 3.00 and 4.00 is a 24.00 combination. The stake is lost if any leg loses, and the combination pays only when every leg wins. The bet builder product offered by some bookmakers — combining markets from one event into a single bet — is a combination bet inside one match, and the same multiplication rule applies.
A payout percentage is what the bookmaker pays back as winnings across all outcomes, and a margin is what the bookmaker keeps. The two add up to 100% on a balanced book. The page’s own example: a two-way market at 1.90 / 1.90 has implied probabilities of 52.63% on each side, an aggregate of 105.26%; the payout is 95.0 % and the overround is 5.26%. The same calculation on a 2.00 / 2.00 book has implied probabilities of 50% on each side, an aggregate of 100%, a payout of 100% and a margin of 0%; a 1.50 / 3.00 book has implied probabilities of 66.67% and 33.33%, an aggregate of 100%, and a margin of 0%. Markets rarely sit at 100%; the realistic floor for a Premier League 1X2 is around 95% payout / 5% margin, and the realistic floor for a curling match market is wider.
The value calculation is the same shape on every market. Implied probability is 1 ÷ decimal odds. The true probability is the punter’s own estimate of the chance. The edge is true probability minus implied probability, and a positive edge is a value bet. Over a long series of bets at positive edge, the punter’s profit converges on the edge times the total stake minus the realised margin on those bets. The variance around the average is wide — a punter with a 5% edge can lose for months before the average comes through — and bankroll discipline is the discipline of betting through that variance without raising stakes to chase.
A few practical notes that follow from the arithmetic. Fractional odds on British racing — 5/1, 11/4 — convert to decimal by adding one, so 5/1 becomes 6.00 and 11/4 becomes 3.75; the conversion is one-way, and a punter who sees only fractional odds should convert before calculating value. Each-way bets are two bets of equal stake on the same selection: one on the win, one on the place. The stake doubles, and the place terms vary by race and operator. Each-way is a horse-racing product more than a curling product, but the doubling of stake applies wherever the operator offers each-way. Rule 4 deductions apply when a runner is withdrawn from a race and the bookmaker adjusts the odds on the remaining runners; the rule is a bookmaker rule rather than a market rule, and the deduction is a percentage taken from the price. Non-runner rules and withdrawal rules sit in the same place — the operator’s terms — and a punter should read them before staking on any sport that has a withdrawal risk, curling included at the team level.
Staking, bankroll and the discipline that sits behind any tip
A staking plan is the rule a punter applies to bet size before the bet is placed, and the plan is what separates betting from tipping. Tipping is the act of choosing a side at a price; staking is the act of choosing how much of the bankroll to risk on that side. Three staking plans dominate British punters’ practice.
Level staking wagers the same unit — say, 1% of bankroll — on every bet. A punter with a £1,000 bankroll on level staking bets £10 on every selection, and the variance on a 5% edge over 100 bets is wide enough to look like losing for the first 30. Level staking is the discipline that lets the punter survive the variance. Proportional staking wagers a fixed percentage of the current bankroll — 1% to 5%, typically — on every bet, so a winning streak grows the stake and a losing streak shrinks it. Proportional staking is the discipline that lets the punter’s edge compound. Kelly staking wagers the edge divided by the price minus one — a 10% edge at 3.00 is a 5% stake — and is the theoretically optimal size for a single bet; the catch is that Kelly assumes an accurate estimate of the edge, and most punters who try Kelly over-estimate the edge and over-stake.
The bankroll is the money a punter has set aside for betting and is willing to lose. The bankroll is not the punter’s spending money and not the punter’s savings; the bankroll is a closed budget for the activity, and the discipline of not topping it up mid-month is the discipline that lets the punter walk away from a bad run. The deposit-limit tools offered by every licensed British bookmaker are a Commission requirement rather than a feature of the brand, and a punter who sets a monthly limit on the first day of using a new bookmaker is not over-engineering the relationship.
The “tip” in curling, as in any other sport, is the selection a tipster has named. A tip is a claim about the chance of an outcome, stated in the language of “I think Sweden wins the World Championship at 6.00” rather than “Sweden wins the World Championship”. The distinction is the discipline of value betting: a tipster who gives only winners is a tipster whose strike rate is suspiciously round, and a tipster who gives losers is a tipster whose record is honest. A punter following tips from a tipster should record the strike rate over at least 200 tips before sizing the bankroll to the tipster’s edge; 50 tips is too few to tell a 53% strike rate from a 47% one, and the variance on 50 is wide enough to look like the wrong answer either way.
Three honest limits of any tipping record. First, no tip is ever certain — a 1.20 shot loses one in five, and a 10.00 shot wins one in eleven. Second, the bookmaker’s margin is on the tipster’s prices too, and a tipster’s strike rate has to clear the margin before it clears the punter’s bankroll. Third, the punter’s own edge is the punter’s, not the tipster’s — a tip that wins because the tipster is right is a tip the punter could not have taken without the tipster’s reasoning, and a tip that loses because the tipster’s reasoning was wrong is a tip the punter could not have foreseen. The right way to read a tipping record is as one input into a punter’s own staking, not as a substitute for it.
The wider British betting frame: tax, advertising and the offshore question
The British punter pays no tax on betting winnings. General Betting Duty is the operator’s tax, currently 15%, and from 1 April 2027 a new remote betting rate of 25% applies within it for remote bets; remote bets on UK horse racing, self-service betting terminal bets, pool betting and in-person betting stay at 15% in the new structure, per the HM Government policy paper of 26 November 2025. Until 1 April 2027 the remote rate stays at 15%, and whether operators pass duty on through their odds is not established. The Commission’s statutory levy is a separate charge on operators, not a tax on the player, and is not visible at the betting slip.
Advertising is not licensed by the Commission; it is regulated through the CAP Code (non-broadcast) and the BCAP Code (broadcast), enforced by the ASA. CAP Code section 16 sets the socially responsible marketing line: no strong appeal to under-18s, no one who is or seems to be under 25 featured gambling or playing a significant role, with an exception for marketing placed where a bet can be made directly. The rule concerns who may appear in an advertisement, not who may bet. “Whistle-to-whistle” — no betting advertisements on TV from five minutes before a live sporting event to five minutes after, before the 9pm watershed, since 1 August 2019 — is an industry code rather than law; horse and greyhound racing are excluded from the rule. The Premier League clubs’ withdrawal of gambling sponsorship from front of shirts (from the 2026/27 season; sleeves and hoardings remain) is voluntary, not law.
Offshore brands are the trade-off a punter makes when choosing a non-licensed operator. A GB licence is compulsory at the point of consumption: providing gambling facilities in Great Britain without the licence the Act requires is an offence under section 33 of the Gambling Act 2005 (on summary conviction up to 51 weeks’ imprisonment, a fine up to level 5, or both; six months in Scotland) — aimed at the operator, not the customer. The trade-off for the customer is the protections the licence brings: GAMSTOP coverage, the Commission complaints route, approved dispute-resolution, the £150 financial vulnerability check threshold, the 10x bonus cap, the credit-card ban. None of those protections apply offshore. Honest framing: licensed means checks, limits and the bonus cap, plus verification before the first bet; unlicensed means none of those and possible loss of funds if the operator decides not to pay. Neither is “the safe choice” by default.
Frequently asked questions about curling betting
How does a punter actually bet on curling?
A punter bets on curling through a licensed British bookmaker’s sportsbook, by selecting a curling match from the operator’s sports menu and choosing a market — match winner, outright tournament winner, handicap, total ends — at a quoted decimal price. Stake × odds is the return on a win; the punter settles the bet through the operator’s standard withdrawal process. The market is thinnest in curling among the major sports, and not every bookmaker prices every event, so the first step is checking the operator’s Wettprogramm for the tournament the punter wants to bet on.
Can a punter bet on curling at all in Great Britain?
Yes. There is no statutory list of permitted bets in Great Britain, and curling is offered by at least one of the licensed operators in this comparison as a stated sport on its menu. The market depth varies by operator and by tournament: outright tournament winner markets on the World Championships and the Olympics are widely priced, individual match markets are priced by the larger sportsbooks, and Continental Tour events are thinnest.
What is a value bet, and why is no tip ever certain?
A value bet is a price that is higher than the true probability of the outcome once the bookmaker’s margin has been taken out — implied probability is 1 ÷ decimal odds, true probability is the punter’s own estimate, and a positive edge is value. No tip is ever certain because a 60% chance bet still loses four times in ten, and the punter’s own estimate of the true probability is itself an estimate. The discipline of value betting is to back only positive-edge bets and accept the variance, not to find a tip that wins every time — no such tip exists.
What is the bookmaker’s margin, and how does it show in the odds?
A bookmaker’s margin is the house take across all outcomes, and the payout is what gets returned as winnings. The two add up to 100% on a balanced book. The margin shows in the odds because implied probabilities — 1 ÷ decimal odds — add up to more than 100%; a two-way market at 1.90 / 1.90 has implied probabilities of 52.63% on each side, an aggregate of 105.26%, and an overround of 5.26%.
How is the return on a bet worked out from stake and odds?
The return on a winning single bet is stake × decimal odds, and the net profit is stake × (odds − 1). On a £100 stake at 3.50, the return is £350 and the profit is £250; on a £10 stake at 1.50, the return is £15 and the profit is £5. On a combination bet — a double, treble or accumulator — the prices of the legs multiply into one price, so a double at 2.00 and 3.00 is a 6.00 combination, and the stake is lost if any leg loses.
How can a punter check that a bookmaker holds a Gambling Commission licence?
The Gambling Commission’s public register is searchable by business name, trading name, domain or account number, and a brand holding a valid entry against a remote general betting standard (real events) licence on the day the bet is placed is a brand holding a valid licence. The domain proves nothing because licensed operators use .com and .co.uk interchangeably. A punter should look up the licence number the operator publishes on its site or app store listing and confirm the entry against the operator’s own trading name and domain before staking.
Tennis, darts & cue sports – Best betting
Content created by the «Best betting» team
